SC Clears Way for Income-Tax Reassessment of Former CJI Y K Sabharwal's Sons
The Supreme Court has upheld income-tax reassessment notices issued to businessmen Chetan and Nitin Sabharwal, sons of former Chief Justice of India Y K Sabharwal, over share transactions linked to their purchase of a prime property on Delhi's Sikandra Road in 2010.
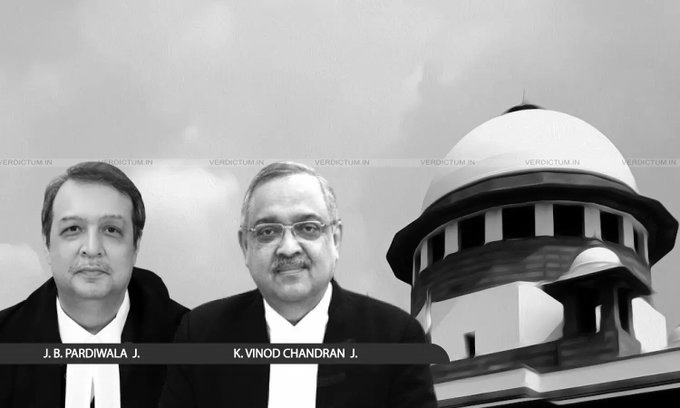
A bench of Justices JB Pardiwala and K Vinod Chandran dismissed four appeals filed by the brothers, upholding the notices issued for assessment years 2008-09 and 2009-10.
In its October 28 judgment, the apex court held that the Income Tax Department had sufficient material to initiate reassessment proceedings on the grounds that taxable income might have escaped assessment.
The notices, issued on March 31, 2015, were based on an investigation report by the Director General of Income Tax. The court said the Assessing Officer had valid reasons to believe that income chargeable to tax had escaped assessment under Sections 147 and 148 of the Income Tax Act, 1961.
The case relates to share transactions undertaken in October 2007, when the Sabharwal brothers and two other shareholders agreed to sell their stakes in Pawan Impex Pvt Ltd and SVIIT Software Pvt Ltd to GYS Real Estate Pvt Ltd for Rs 195 crore and Rs 60 crore, respectively. Each seller was entitled to a one-fourth share of the consideration.
A subsequent investigation raised concerns that the share valuations were significantly higher than what could be justified by the underlying land and buildings.
The department also found that a substantial portion of the sale proceeds was used to acquire a property on Sikandra Road in April 2010. The brothers claimed exemption from capital gains tax under Section 54F of the Act on the investment.
The Supreme Court observed that reassessment proceedings did not require the officer to conclusively establish income escapement at the notice stage. It also said courts could not examine the sufficiency of the reasons recorded by the Assessing Officer.
The ruling allows the tax authorities to proceed with the reassessment; it does not determine the final tax liability of the brothers.